Buyside Liquidity
Chapter 1 — Buyside Liquidity
1. Definition
Buyside liquidity is the population of resting buy orders sitting above the current price. [LQ-01]
Read that as a description of orders, not of a level. The most common error in this whole subject is to draw a line at an old high and call the line liquidity. The line is a mark you make. The liquidity is the orders — who placed them, why, and what happens when price arrives.
This opens Volume 2, which is about liquidity: where orders rest in a market and what that does to price. The volume works through fifteen concepts in registry order, LQ-01 to LQ-15, and this is the first of them. It assumes you have read nothing else.
2. Institutional reasoning
Two sources, one region
Buy orders above price come from two different people who want opposite things.
The stops of short positions. Somebody sold short, expecting price to fall. To limit the damage if they are wrong, they place a protective stop above their entry. A stop on a short position is a buy order — it has to be, because closing a short means buying back what you sold. That trader does not want it filled.
The breakout orders of buyers. Somebody else is waiting for price to clear an old high before committing. They place a buy order above that high, because they want to be in only if price gets there. That trader is hoping it fills.
One is defending a loss, the other is opening a position. Their intentions are opposite and their orders are identical: buy, above current price, in the same region. That is why the region matters more than either participant does.
Why a large seller cares
Now take the other side. Suppose an institution needs to sell a genuinely large position — more than the market can absorb at the current price without moving badly against it.
It needs buyers. Not one buyer; a concentration of them, all willing to buy at roughly the same place. And there is exactly such a concentration sitting above price, made of stops and breakout orders that will fire automatically when reached.
Price moving up into buyside liquidity is what makes a large sale possible. The buying that gets triggered up there is the other side of the trade. This is the whole mechanism, and there is nothing mystical in it: someone with size to move goes where the orders are, because that is the only place the size can go.
Notice the direction, because it inverts what most beginners assume. Price rising into an old high is not automatically strength. It may be the delivery that lets somebody sell.
What this does not tell you
The mechanism explains why price is drawn toward these regions. It says nothing about what happens after it arrives — whether a seller was waiting, whether they had size enough, or whether price simply carries on. Section 5's third example is that case, and it costs money.
3. Recognition
What makes a region identifiable
Orders do not accumulate at arbitrary prices. They accumulate where traders can see something — and what they see is structure.
This concept depends on MS-01, the swing point: a high with lower highs on either side of it, a visible turning point on the chart. A swing high is agreed-upon in a way that an arbitrary price is not. Two traders looking at the same chart will identify the same swing high; they will not independently pick the same random level.
Structure makes a location identifiable, and identifiable locations are where orders collect. That is the entire relationship between the two concepts. Buyside liquidity does not rest above price generally — it rests above the highs that people can name.
The shapes, named here and taught later
The same population takes recognisable shapes, and this volume gives each its own chapter:
| Shape | What it is | Where |
|---|---|---|
| LQ-04 Old high and old low | A single prior high with orders above it | Ch. 4 |
| LQ-05 Equal highs and equal lows | Two or more highs at nearly the same price | Ch. 5 |
| LQ-03 Liquidity pool | What a set of these becomes when treated as one target | Ch. 3 |
Do not go looking for those distinctions yet. Recognise the population first.
The mirror, stated once
Everything in this chapter inverts exactly below price. Sellside liquidity is the population of resting sell orders below the current price — the stops of long positions and the breakdown orders of sellers, drawing a large buyer the way this draws a large seller. That is LQ-02, the next chapter: same mechanism, opposite direction. Whether the two sides behave alike is a separate question, and Chapter 2 raises it.
The tests
- Are you looking above the current price? Buyside is above. Always.
- Is there an identifiable swing high — a high with lower highs either side — or are you marking a price you chose?
- Can you name who has orders there? Stops of shorts, breakout buyers, or both.
- Would a large seller be able to fill there? If nothing is resting, there is nothing to fill into.
- Has the region already been traded through? Once orders are filled they are gone, and a level that has been run is not the pool it was.
4. Workflow
You are marking, not trading. This chapter contains no entry rule and Volume 2 contains no model.
- Set your chart to New York time. Every time reference in this series is New York time.
- Working left to right, identify the swing highs — highs with lower highs on both sides.
- Mark each with a horizontal line extended to the right. That line is your reference to the population, not the population itself.
- For each, write down which orders you believe rest there: stops, breakout entries, or both.
- When price trades through one, mark the date and note what happened next — reversal, continuation, or nothing.
- Remove marks that have been run, or annotate them as taken. A chart full of dead levels teaches you nothing.
Abort conditions. Nothing is entered here, so the failure is not a losing trade — it is a chart so covered in lines that every move looks like it is reaching for something. If you cannot say who has orders at a level, delete the level.
5. Worked examples
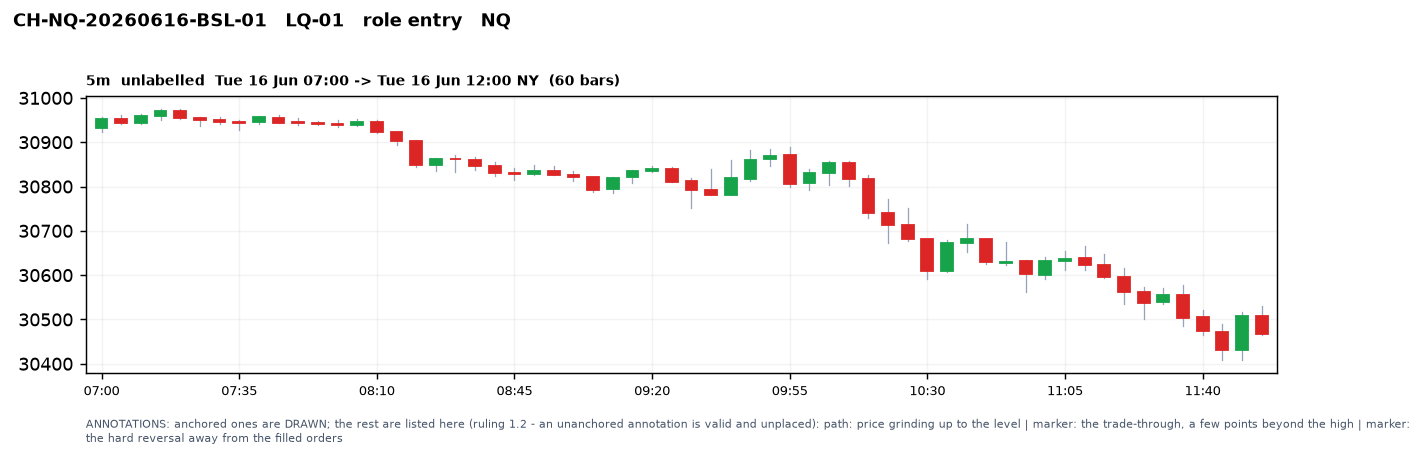
CH-NQ-20260616-BSL-01 — the population doing its job. A clear swing high sits above the current price, formed two sessions earlier and untouched since. Price grinds up to it, trades a few points through, and reverses hard. What was seen: an identifiable high with orders resting above it. What was done: the level marked, nothing traded. What happened: price reached the orders and turned away from them — the textbook case, and the one that makes the idea look easy.
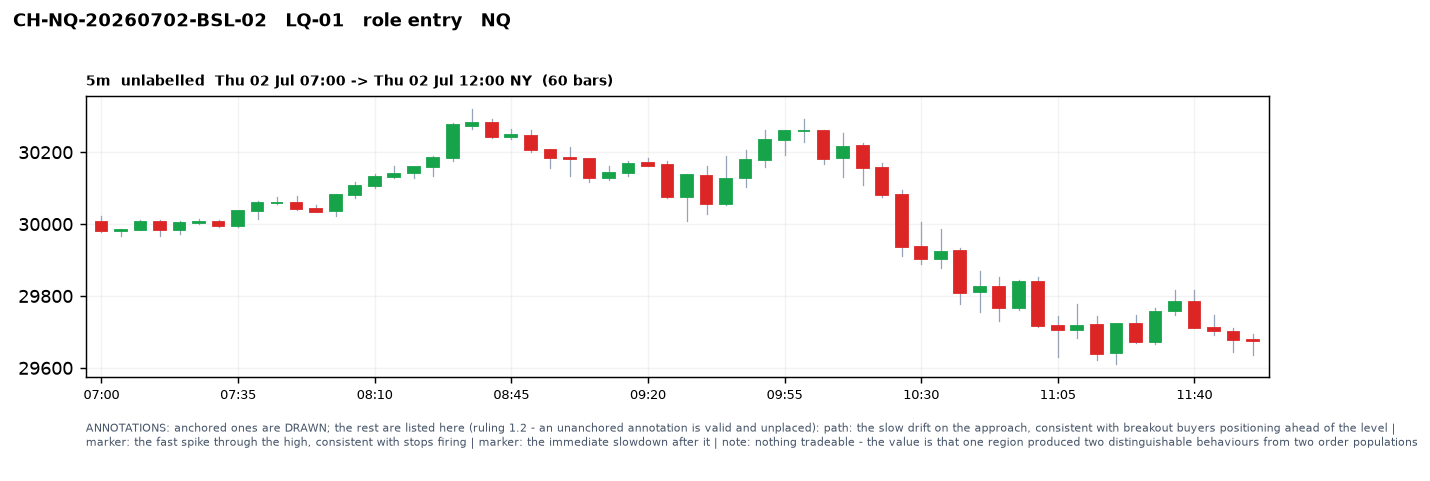
CH-NQ-20260702-BSL-02 — two sources, visible separately. Price approaches an old high tested twice before. On the approach there is a slow drift, then a fast spike through the high, then an immediate slowdown. What was seen: the drift is consistent with breakout buyers positioning ahead of the level, the spike with stops firing. What was done: both noted. What happened: nothing tradeable — the value is that one region produced two distinguishable behaviours from two order populations.
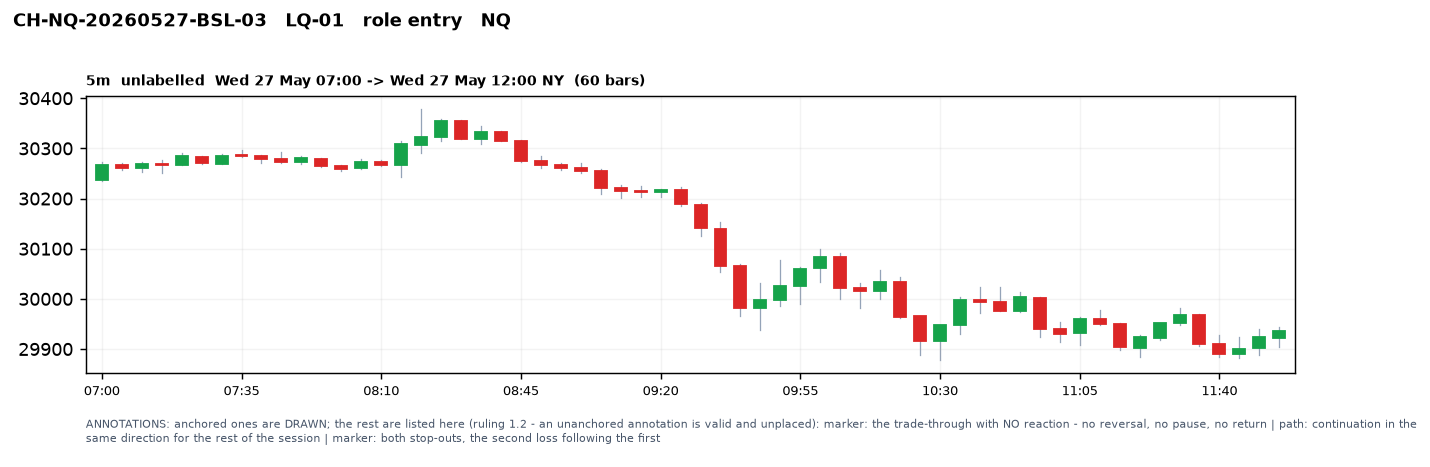
CH-NQ-20260527-BSL-03 — the level that was taken and simply kept going, and what it cost. A well-formed swing high is marked. Price reaches it, trades through, and does not react at all: no reversal, no pause, no return. It continues in the same direction for the rest of the session. A trader who had learned "price reaches for liquidity and then turns" sells into the level, is stopped out above it, sells again on the next push expecting the turn that is overdue, and takes a second loss.
Liquidity being present tells you nothing about what price does after it is taken. The orders were there and they were filled — the concept was correct. What was invented was the second half: that being filled implies a reversal. Nothing in this chapter claims that, and no chapter in this book will claim it without a measurement behind it. A concept that explains where price goes is not a concept that predicts what happens when it arrives.
6. Exercises
- On the last five trading days, mark every swing high on a 5-minute chart. Count them.
- For each, write one sentence naming who you believe has orders above it.
- Identify every level that price traded through in those five days. For each, record what happened in the following thirty minutes: reversed, continued, or neither.
- Count how many of those three outcomes you got. Most readers are surprised by the "continued" column.
- Find one level you marked that you now think should not have been marked. Explain what made it look identifiable when it was not.
- Write one sentence explaining buyside liquidity to someone who has never seen a chart, without using the word "level".
7. Manual backtesting
| Date | Swing high marked | Approached? | Traded through? | Reaction in 30 min | Normal session? |
Fill it for forty consecutive trading days on one instrument. Mark levels before they are approached, never afterwards — a level identified in hindsight is a memory, not a test.
Then compute three numbers: how often a marked level was approached at all, how often an approach became a penetration, and how the outcome after penetration divided between reversal, continuation and neither.
That third number is the important one, and it is the one nobody quotes. If continuation is common on your instrument, then every rule you later read about liquidity being "taken and rejected" describes a subset of cases, and you will want to know how big that subset is before you build anything on it.
Forty days is a first estimate. Write the sample size next to the result, always.
8. Common mistakes
- Treating the line as the concept. The line is your bookmark; the orders are the concept. Correction: for every level marked, name who has orders there or delete it.
- Assuming a reach implies a reversal. Correction: section 5's third example. Measure the continuation rate yourself before assuming.
- Marking arbitrary prices. If there is no swing high, there is no reason for orders to be there. Correction: structure first, mark second.
- Reading a rise into an old high as strength. It may be the move that lets somebody sell. Correction: hold both readings until something else decides between them.
- Keeping levels after they are run. Filled orders are gone. Correction: annotate or remove taken levels the same day.
- Thinking sellside is a different mechanism. It is the same one, mirrored. Correction: Chapter 2.
9. Cross references
Depends on:
- MS-01 Swing point (Vol. 3, Ch. 1) — supplies the identifiable structure that lets orders accumulate
Feeds — three lines of this book start here:
- LQ-03 Liquidity pool (Ch. 3) — what a set of these becomes
- LQ-09 Liquidity raid (Ch. 9) — what happens when price takes one
- NR-01 Draw on liquidity (Vol. 5, Ch. 1) — what it means for direction
Closely related:
- LQ-02 Sellside liquidity (Ch. 2) — the mirror
- LQ-04 Old high and old low (Ch. 4), LQ-05 Equal highs and equal lows (Ch. 5) — the shapes this population takes
10. Quantitative mapping
Not yet formalised. LQ-01 sits at Stage 2: the concept is operationally defined and can be marked on a chart consistently, and it has not been quantitatively specified.
The registry holds no quantitative-specification reference for this entry at all — not a broken one, not a pending one. There is no section anywhere that says what counts as buyside liquidity in code.
That is worth sitting with, because this is a Stage 4 concept in everything but paperwork: it is marked on live charts daily and three registered concepts depend on it. Being obvious is not the same as being specified. A rule you can apply by eye is not yet a rule two engineers would implement identically, and the difference only becomes visible when somebody tries.
ICT-QS candidate — does marked buyside liquidity behave differently from unmarked price? On NQ: the approach rate to identifiable buyside regions, the penetration rate once approached, and the distribution of outcomes after penetration, each measured against equivalent unmarked regions as a control. Unmeasured. Section 7 is its manual form, and the control is the part most readers would leave out — without it you learn what price does near old highs, not whether old highs matter.
charts: [] stands, as across this book. The volume-wide chart pass is parked.
LQ-01UNEXAMINEDread the honesty sentence
Not yet formalised. LQ-01 sits at Stage 2: the concept is operationally defined and can be marked on a chart consistently, and it has not been quantitatively specified.